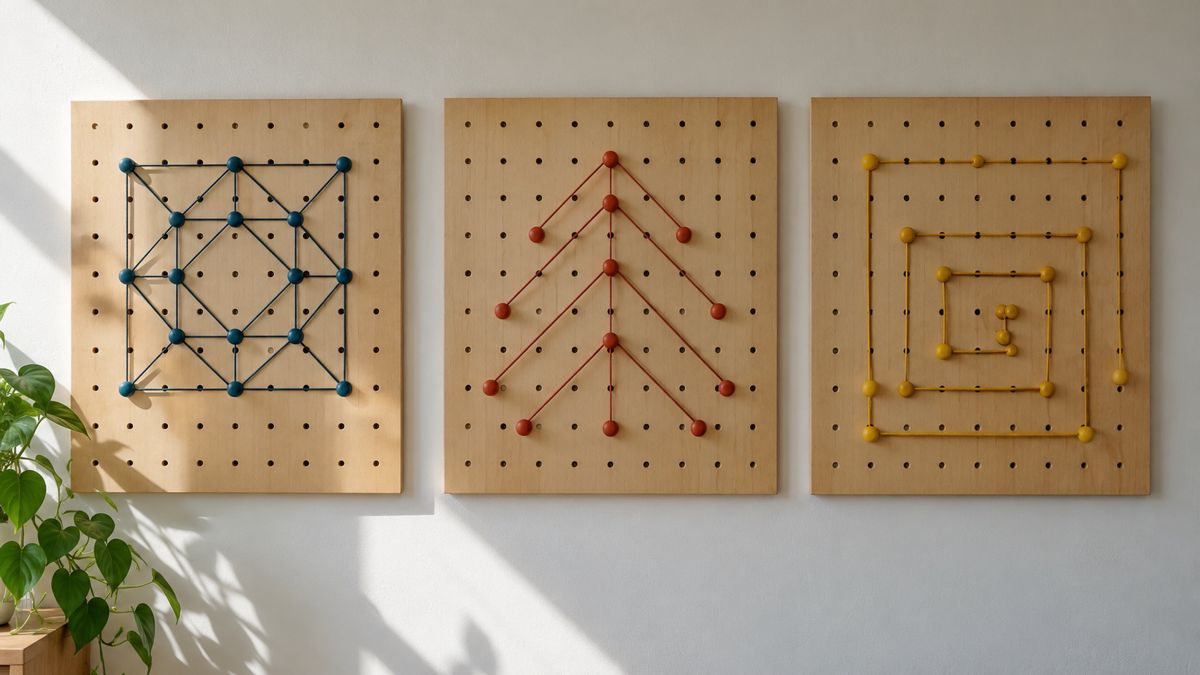
Short answer: a binary plan pays on two legs, a unilevel plan pays on levels in one wide line, and a matrix plan limits how many people fit under each member and fills the spots in order. None of the three is better in general. The right one depends on your products, how your distributors actually sell, and what your lawyer is willing to sign off on. Whichever you pick, a legitimate plan pays mainly for real retail sales of real products to real customers.
This article explains each structure in plain terms, shows a small worked example for each, and lists what a software team has to get right when it turns the plan into code. It is not legal advice, and the examples use made-up points to show the mechanics, not what anyone earns.
What a compensation plan really is
A compensation plan is a written set of rules that says who gets paid, for which sales, how much and when. The shape of the organization chart (the genealogy) is only one input. The rest is volume definitions, ranks, qualifications, caps, payout dates and what happens when an order is refunded. Two companies can both say they run a unilevel plan and have completely different payouts because those details differ.
That is why we ask for the plan document before we talk about screens. If the rules are written down in full, they can be built and tested. If they only exist in a spreadsheet and in someone's head, the first job is to write them down.
Binary plans: two legs and pairing
In a binary plan every member has at most two direct positions, a left leg and a right leg. New people are placed under one of them, and the volume in each leg is tracked separately. Bonuses are usually paid on matched volume: the smaller of the two legs.
An illustrative example: if the left leg has 300 points and the right leg has 200 points, the matched volume is 200 points. The extra 100 points on the left may carry forward to the next period, or may expire, depending on the plan. Plans often add a daily or weekly cap on how much pairing can be paid.
The details that cause the most bugs are carry forward, flush rules, caps, and the placement rule (who decides which leg a new member goes to, and what happens to spillover). Each one has to be stated precisely. Our page on binary plan software covers how we build these rules.
Unilevel plans: one wide line, paid by depth
In a unilevel plan a member can sponsor as many people as they like on their first level. Each of those can sponsor others, which forms the second level, and so on. The plan pays a percentage of sales volume down to a set number of levels.
An illustrative example: a plan might pay a higher percentage on level one and smaller percentages on levels two to five, and nothing below that. Some plans add compression, which skips over inactive members so that qualified people higher up still receive pay for the active levels below them.
Unilevel structures are easy to explain to new distributors because the tree matches the real sponsorship. The rules to pin down are the number of paid levels, what counts as active, how compression works and whether personal purchases count toward volume. Read more on unilevel plan software.
Matrix plans: limited width, filled in order
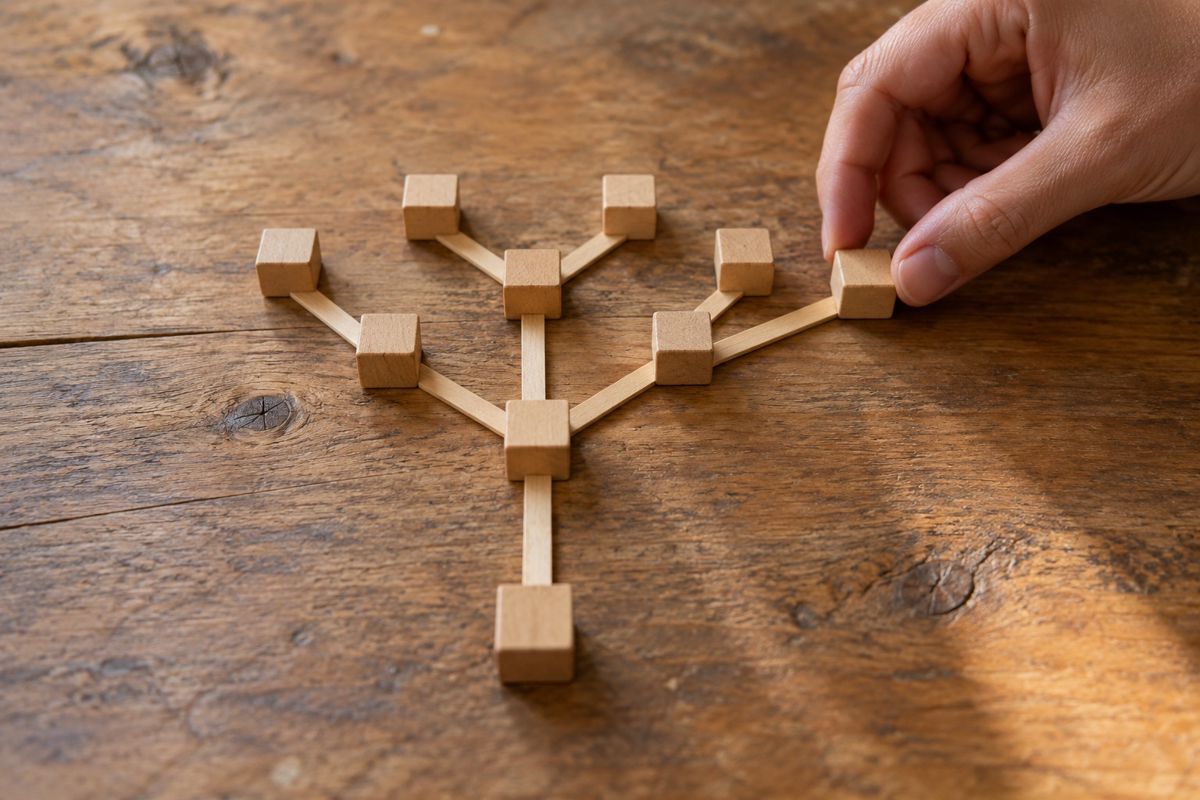
A matrix plan caps the width of each member's first level and sets a fixed depth. A 3 by 7 matrix, for example, allows three people on the first level and pays down seven levels. When a member's first level is full, new sign-ups are placed under someone else according to the placement rule. This is often called spillover.
Because positions fill in a set order, the placement logic is the heart of a matrix plan. Is placement automatic by sign-up time, by sponsor choice, or by the company? What happens when a member leaves or is removed? What happens to the positions below them? These cases are rare, but they happen, and the software needs a documented answer for each. See matrix plan software for how we approach it.
Hybrid plans
Many real plans combine ideas: a unilevel override on a binary base, a fast start bonus for the first weeks, a rank bonus, a leadership pool. These can be perfectly sound, but every added rule multiplies the number of edge cases. If you are designing a hybrid, build it as a list of separate bonuses with a clear name, formula and cap for each, so that each one can be tested and, if needed, changed on its own. We describe that approach on our hybrid plans page.
How to choose between them
Start from the business, not from the structure. A few questions help:
- Who is your customer: mostly outside buyers, or mostly the distributors themselves? A plan that depends on distributors buying for themselves is a warning sign.
- Is your product repeat-purchase, such as consumables, or a one-time purchase? Repeat products suit volume-based plans better.
- How simple must the plan be to explain in one conversation?
- Which markets will you sell in, and what do the local direct selling rules there require?
- Can your team support the plan day to day, including disputes and refunds?
The answers often matter more than the choice of binary, unilevel or matrix. A simple plan that pays for retail sales and that you can explain in two minutes usually causes fewer disputes than a clever one.
What the software has to get right
Whatever the structure, a good build does the same few things. It stores money as exact decimals, not floating point numbers. It records every commission with the order, the rule and the period that produced it, so that a distributor or an auditor can trace it. It handles refunds by reversing the related commissions. And it lets you run a period in preview before any money moves. We go deeper on this in our article on commission engine design.
Timelines and prices for plan software are typical, they depend on scope and on timely feedback, and a written quote follows a scoping conversation. You can see the typical ranges on the pricing page. The client owns the code and the accounts it pays for.
A note on legitimacy
We build software only for direct selling businesses whose pay comes from genuine retail sales of real products. We do not build schemes that pay mainly for recruiting, schemes sold as investments with fixed returns, or cash-gifting and board schemes. Direct selling is regulated, and you should have your plan and any income disclosures reviewed by a lawyer who knows your markets. Our compliance page explains how we work with your reviewers.
If you want to talk through which structure fits your products, chat with us on WhatsApp at +1 (929) 450-3261 and tell us what you sell, where, and how the plan pays today.